Surgery Abroad Complications: What Insurance Covers & Doesn’t
You’ve booked surgery abroad expecting to save thousands. But if a complication strikes, will your travel insurance actually cover the hospital bill — or will you face a six‑figure debt? Most policies exclude elective surgery complications, leaving patients responsible for emergency care, evacuation, and follow‑up. Without the right coverage, a complication can cost more than the procedure itself.
By the end of this guide, you’ll understand exactly what insurance does and doesn’t cover for surgery abroad, and how to build a three‑layer safety net that protects you from the biggest financial risks. We’ll compare the three main insurance types, break down the most common exclusions, and walk through a step‑by‑step preparation plan.
Key Takeaways
Most travel insurance policies exclude complications from elective surgery abroad, leaving patients liable for $50,000+ in emergency costs.
- The Insurance Safety Net Framework has three layers: Baseline Coverage, Complication Buffer, and Evacuation Parachute.
- Medical evacuation is rarely covered by standard travel insurance; a dedicated policy or rider with at least $250,000 coverage is essential.
- Post‑op follow‑up and revision surgery at home are almost never covered — plan for these costs before you travel.
Understanding Insurance Coverage for Surgery Abroad
Standard travel insurance typically excludes complications from elective surgery abroad. Most policies are designed for tourists, not medical travelers. As a result, if you need emergency treatment for an infection or a poor surgical outcome, you will likely pay out of pocket (wmedtour.com, 2024). This section breaks down the three main insurance types and their coverage for surgery abroad.
Does Insurance Cover Cosmetic Surgery When Done Abroad?
The short answer is almost always no — unless you have a specialized medical tourism policy. Domestic health insurance almost never covers elective cosmetic procedures performed outside your home country. Standard travel insurance excludes planned surgery entirely, and international health insurance may only cover procedures deemed medically necessary.
To see how this plays out in practice, consider a patient who travels to Mexico for a tummy tuck. Post‑op, she develops a severe infection requiring hospitalisation for five days. Travel insurance denies the claim because the infection is a known complication of a planned elective procedure. The bill: $45,000.
The key distinction is between “complication coverage” and “procedure coverage.” Even policies that advertise medical benefits typically only cover emergencies unrelated to your planned surgery. Dr. Parada’s analysis confirms that insurance routinely excludes cosmetic surgery complications, even when performed domestically.
With that baseline, let’s compare the three policy types side by side.
Travel Insurance vs. International Health vs. Medical Tourism Insurance
| Coverage Type | Elective Surgery | Complications | Medical Evacuation | Pre‑existing Conditions |
|---|---|---|---|---|
| Travel Insurance | No | Excluded | Limited (~$50k) | Usually excluded |
| International Health | Only if medically necessary | Maybe | Yes | Possible with waiting period |
| Medical Tourism Insurance | Not the procedure itself | Yes | Yes (~$250k+) | Sometimes with screening |
The table reveals a critical gap: even the best travel insurance leaves you exposed. Medical tourism insurance is the only type designed specifically to cover elective complications. American Visitor Insurance notes that visitor medical policies typically exclude planned surgery entirely.
Now let’s examine the most common exclusions in detail.
Common Exclusions You Need to Know
Understanding what’s excluded is just as important as knowing what’s covered. Here are the most common gaps:
- Elective/cosmetic procedures — Almost always excluded, even when performed domestically.
- Pre‑existing conditions — May be excluded or require a waiver with additional premium.
- Experimental treatments — Stem cell therapy, unproven interventions, and clinical trial procedures.
- Complications from elective surgery — The critical gap. Even if the policy covers emergency medical care, it may specifically exclude complications arising from planned elective procedures.
- Follow‑up care at home — Not covered by travel insurance, and often excluded by domestic insurance.
- Revisional surgery — Rarely covered, even by medical tourism policies, unless explicitly stated.
Which surgery is not covered by insurance? Elective cosmetic surgery tops the list — even when performed domestically. wmedtour.com confirms that medical tourism insurance may cover complications, but standard travel insurance does not.
Understanding what’s not covered leads to the next question: what are the real risks you’re facing?
The Real Risks of Surgery Abroad
Every surgical procedure carries inherent risks, but medical tourism amplifies several of them. Limited follow‑up care, language barriers, varying standards of infection control, and the difficulty of coordinating emergency treatment in an unfamiliar healthcare system all increase the likelihood of poor outcomes. This section shows why you need the Complication Buffer layer of the Safety Net.
The Top 3 Riskiest Surgeries in Medical Tourism
-
Brazilian Butt Lift (BBL) — This procedure carries the highest risk of fat embolism, where injected fat enters the bloodstream and blocks the pulmonary artery. Mortality rates for BBL are among the highest of any cosmetic procedure, and emergency treatment requires specialized equipment not available in all international facilities.
-
Tummy Tuck (Abdominoplasty) — High infection and seroma rates, combined with a long recovery period, make this procedure particularly risky abroad. Patients often develop wound complications after returning home, when follow‑up with the original surgeon is no longer feasible.
-
Complex Spinal Fusion — High complication rates and the need for extended, specialised follow‑up make this procedure dangerous in a medical tourism context. Post‑operative imaging, physical therapy, and monitoring require consistent access to the surgical team.
UTSW Medical Center reports that medical tourism for plastic surgery carries increased risks of complications compared to domestic procedures. Infection rates for medical tourists can be 2–3 times higher than for domestic patients, adding $20,000–$50,000 in emergency care costs.
Knowing which surgeries carry the highest risk, let’s look at what happens when a medical emergency strikes abroad.
What Happens in a Medical Emergency Abroad?
Imagine this scenario: three days after your procedure, you develop a high fever and severe abdominal pain. Your hotel calls an ambulance, and you’re rushed to a local hospital. The doctor suspects an internal infection and admits you to the ICU. Then the billing department arrives.
In most international hospitals, you’ll be asked for a deposit or proof of insurance before treatment continues. Travel insurance typically denies the claim because the complication stems from a planned elective procedure. You have three options: pay out of pocket (a week in ICU can exceed $50,000), use a local public hospital (variable quality and long waits), or rely on emergency savings.
What happens if you have a medical emergency in another country? You will almost certainly have to pay upfront unless you have specialized coverage that includes complication protection. TravelHealthPro, the UK government’s travel health service, advises medical tourists to arrange comprehensive insurance before travelling.
These emergency costs are just the beginning. Let’s talk about the hidden financial pitfalls.
The Hidden Costs of Uncovered Complications
Beyond the immediate hospital bill, several other costs can quickly accumulate:
- Emergency room visit — $5,000–$20,000 depending on the facility and interventions needed.
- ICU stay per day — $3,000–$10,000, often requiring a minimum 3‑day stay.
- Surgery to correct complication — $10,000–$50,000 for revisional procedures.
- Additional travel and accommodation — Extended recovery may require weeks in a hotel near the hospital.
- Lost wages from extended recovery — Complications can double or triple your time away from work.
- Follow‑up care after returning home — Ongoing treatment, medication, and monitoring.
It’s also worth checking whether the complication qualifies under the policy’s definition of “critical illness.” Many insurance policies define critical illness narrowly — heart attack, stroke, cancer — and a surgical complication like infection or seroma typically doesn’t meet that threshold.
Be aware: if things go wrong abroad, you will usually have to pay for treatment. Philadelphia Liposuction notes that complications from liposuction abroad often require costly revisional surgery not covered by standard insurance.
If a complication requires moving you to a better facility or back home, you enter the world of medical evacuation — which brings us to the third layer of your safety net.
Medical Evacuation and Repatriation: The Cost of Getting Home
If a complication requires advanced care not available locally, medical evacuation becomes your only option — and it’s extraordinarily expensive. A medical evacuation from Bangkok to Los Angeles can cost $150,000–$250,000 (State Department, 2024), far exceeding common $100,000 policy limits. This section explains what evacuation insurance covers and why the third layer of your safety net — the Evacuation Parachute — is essential.
Is $100,000 Enough for Medical Evacuation?
No, $100,000 is often insufficient for a long‑distance or complex medical evacuation. Here’s what typical scenarios cost:
| Evacuation Type | Typical Cost Range |
|---|---|
| Regional evacuation (within country) | $10,000–$50,000 |
| International air ambulance | $50,000–$200,000+ |
| Helicopter transport from remote area | $15,000–$30,000 |
If you are in Thailand and need an air ambulance to Los Angeles, costs typically start at $150,000. U.S. State Department guidance warns that medical evacuation can cost $50,000–$250,000 or more. A more realistic coverage target is $250,000–$1,000,000.
Now let’s look at what evacuation insurance actually includes — and what it doesn’t.
What Does Medical Evacuation Insurance Actually Cover?
Medical evacuation insurance typically covers three types of transport: air ambulance (a medically equipped aircraft with onboard medical staff), commercial flight with a medical escort (a nurse or doctor accompanying you on a regular flight), and ground ambulance coordination at both ends for seamless hospital‑to‑hospital transfer.
The gold standard is bed‑to‑bed service, where the provider coordinates transport directly from your foreign hospital bed to a hospital near your home. Some policies make direct payments to hospitals and evacuation providers, which is far more valuable than reimbursement‑only policies that require you to pay upfront.
However, not all policies cover every scenario. Some only authorize evacuation if the local hospital lacks adequate facilities — meaning if the hospital can technically treat you, even at lower quality, the policy may deny coverage. Others require a doctor’s recommendation and pre‑approval.
InternationalInsurance.com notes that evacuation insurance for expats often includes bed‑to‑bed service, but it’s critical to confirm this before purchasing.
In the worst case, evacuation isn’t possible. That’s where repatriation of remains insurance comes in.
Repatriation of Remains: A Difficult but Necessary Topic
Repatriation of remains refers to preparing and returning a deceased person’s body to their home country. This process involves embalming, documentation, air transport, and coordination with local authorities. Costs typically range from $5,000 to $20,000 depending on the destination and complexity.
Many travel insurance policies include a small amount for repatriation — often around $10,000 — but this may not be enough for complex cases involving multiple jurisdictions, legal holds, or specialized transport. It’s worth checking the specific amount in any policy you’re considering and adding a dedicated rider if the coverage seems insufficient.
State Department repatriation guidance confirms that repatriation of remains is a standard but limited benefit in travel insurance. If you’re travelling for surgery, consider increasing this coverage or ensuring your medical tourism policy includes a robust repatriation provision.
Now that you understand the risks and the evacuation need, let’s look at the specialized policies designed to fill these gaps.
Specialized Medical Tourism Insurance: Your Safety Net
Medical tourism insurance is the only policy type that typically covers complications from elective surgery (wmedtour.com, 2024), filling the critical gap left by travel insurance. This section introduces the three‑layer Safety Net Framework and provides a checklist to evaluate any policy.
The Insurance Safety Net Framework: Three Layers of Protection
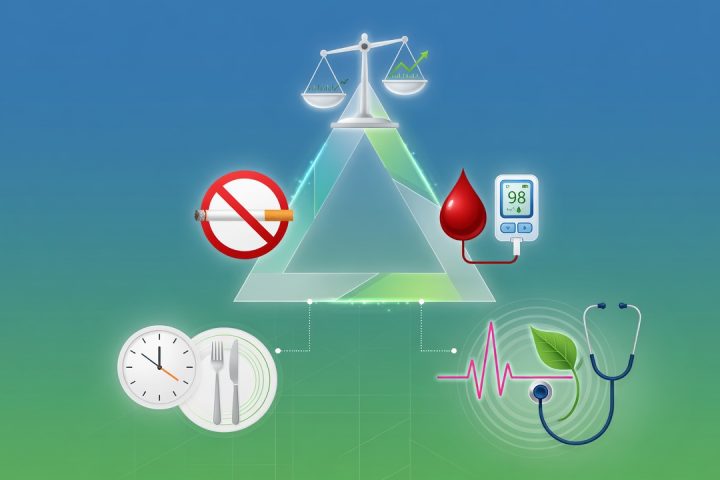
Think of your coverage as a three‑layer safety net, each layer designed to catch a different type of risk.
Layer 1 — Baseline Coverage. This is your standard travel or international health insurance. It covers medical emergencies unrelated to your elective procedure — a car accident, food poisoning, or a sudden illness. But it specifically excludes complications of the surgery itself. Most medical tourists stop at Layer 1, unaware of the gap beneath their feet.
Layer 2 — Complication Buffer. Specialized medical tourism insurance fills the gap. It covers emergency treatment of complications arising directly from the elective procedure — infections, hematomas, poor surgical outcomes, and revisional care. This is the layer that protects you from the $45,000 infection bill.
Layer 3 — Evacuation Parachute. Medical evacuation and repatriation coverage ensures that if the local healthcare system can’t handle your complication, you can be transported to a better facility or back home. This layer covers air ambulance, medical escort, and repatriation of remains.
Most people only have Layer 1. The goal of this guide is to help you add Layers 2 and 3 before you travel.
Now let’s apply this framework to understand exactly what a medical tourism insurance policy should include.
What Does Medical Travel Insurance Not Cover? (The Gap Checklist)
Use this checklist to evaluate any medical tourism insurance policy:
- ☐ Explicit coverage for complications of elective/cosmetic surgery. Not all policies include this — confirm in writing.
- ☐ Medical evacuation with a minimum of $250,000 coverage. Regional evacuation may be cheaper, but international air ambulance can exceed $200,000.
- ☐ Repatriation of remains (at least $20,000). Standard travel policies often cap this at $10,000.
- ☐ Direct hospital payment (not just reimbursement). Direct pay policies are far easier to use in an emergency.
- ☐ No exclusion for pre‑existing conditions (or a waiver option). Some policies require a medical screening.
- ☐ Coverage for revisional surgery that is medically necessary. Not all policies include this — verify the definition.
- ☐ 24/7 assistance hotline with multilingual staff. In a crisis, you need someone who can coordinate care in your language.
wmedtour.com emphasizes that a comprehensive medical tourism insurance policy should include complication coverage, evacuation, and direct pay features.
With this checklist in hand, you’re ready to evaluate policies. Let’s look at a quick comparison.
Key Features to Look for in a Policy
The most critical feature is complication coverage — the policy must explicitly state that it covers medical complications arising from elective surgery. Without this, Layer 2 of your safety net is missing.
| Feature | Basic | Standard | Premium |
|---|---|---|---|
| Complication coverage | ☐ Not included | ☑ Up to $50,000 | ☑ Up to $100,000 |
| Evacuation limit | $50,000 | $250,000 | $1,000,000 |
| Direct payment | Reimbursement only | Direct pay | Direct pay |
| Pre‑existing conditions | Excluded | Waiver available | Waiver available |
| Revisional surgery | Excluded | ☐ Not included | ☑ Up to $25,000 |
InternationalInsurance.com notes that international insurance can be tailored for expats needing surgery abroad, but the coverage details vary significantly by provider.
Compare at least three policies using the checklist above before purchasing.
Understanding the policy is one thing. Now let’s turn that knowledge into action with a step‑by‑step preparation plan.
How to Plan and Prepare for a Safe Surgery Abroad
A comprehensive pre‑surgery plan reduces complication risk by ensuring proper follow‑up and coverage are arranged in advance (UTSW, 2024). This planning guide ensures you have all three layers of the Safety Net before you travel.
Your 10‑Point Pre‑Surgery Checklist
- Research and select an accredited hospital. Look for Joint Commission International (JCI) accreditation or an equivalent global quality standard.
- Verify your surgeon’s credentials and hospital infection rates. Request board certification, years of experience, and published complication data.
- Purchase specialized medical tourism insurance. Use the Safety Net checklist from the previous section to evaluate options.
- Confirm your policy’s complication coverage for the specific procedure. Ask the insurer directly: “Does this policy cover infections, hematomas, and revisional surgery from my procedure?”
- Arrange medical evacuation coverage with at least $250,000 limit. If your policy offers less, consider a supplemental evacuation rider.
- Plan travel and accommodation with recovery time in mind. Book a hotel near the hospital for at least 10–14 days post‑op.
- Transfer medical records to the foreign hospital and a local doctor at home. Ensure both teams have your complete history.
- Establish a follow‑up care plan with a local physician before you go. Schedule an appointment for 1–2 weeks after your return.
- Budget for potential uncovered costs. Set aside an emergency fund of at least $10,000.
- Inform your domestic health insurance about your plans. Some policies offer limited coverage for overseas emergencies — know what’s excluded.
UTSW Medical Center recommends a pre‑surgery checklist that includes facility accreditation and complication planning.
A checklist is only useful if you know what each item means. Let’s dive into facility selection.
Choosing an Accredited Facility and Surgeon
JCI accreditation is the global benchmark for hospital quality. It means the facility meets international standards for patient safety, infection control, and clinical protocols. When researching hospitals, look for their JCI certificate number and verify it on the JCI website.
Beyond accreditation, check the hospital’s infection rates, readmission rates, and patient reviews. A low cost may reflect lower quality standards — pay attention to warning signs like unusually high patient volumes or negative reviews about post‑operative care.
For the surgeon, verify board certification in the relevant specialty, years of experience performing the specific procedure, and membership in recognised international societies. Request a virtual consultation — it’s an opportunity to assess communication quality, transparency about risks, and willingness to share complication data.
TravelHealthPro, the UK government’s official travel health service, recommends checking hospital accreditation before travelling.
With the right facility and insurance secured, it’s time to think about the often‑overlooked part: what happens after you return home.
Arranging Insurance, Travel, and Post‑Op Care
Coordinate your insurance purchase with your travel booking. Some policies require purchase before departure and only become active once you’ve left your home country. Buy insurance that covers trip interruption — if complications delay your return, the additional accommodation and flight change fees can add up.
Be aware: if things go wrong abroad, you will usually have to pay for treatment. Build an emergency fund of at least $10,000 to cover deductibles, upfront deposits, and uncovered costs.
Perhaps the most overlooked step is arranging post‑op care at home. Before you travel, identify a local primary care physician or specialist who can manage follow‑up. Transfer your medical records to them and schedule an appointment for 1–2 weeks after your return. Understand that this follow‑up care is almost certainly not covered by insurance — it becomes your responsibility.
InternationalInsurance.com advises expats to ensure their policy covers trip interruption and follow‑up care coordination.
Even with the best preparation, complications can happen. Here’s how to navigate them if they do.
Navigating Complications and Follow‑Up Care After Returning
The cost of treating a post‑surgery infection at home can reach $30,000 — and most travel insurance policies will deny the claim (Philadelphia Liposuction, 2024). Layer 2 (Complication Buffer) is tested hardest when you’re back home and uncovered.
You’ll Need Ongoing Care — Will Insurance Cover It?
Almost certainly not. Once you return home, follow‑up care for an elective surgery abroad is considered part of the original elective procedure — and domestic insurance explicitly excludes this. Even if the complication is medical (an infection, for example), the insurance company argues it stems from an elective, non‑covered procedure.
Here’s a realistic scenario: A patient returns from Thailand with a wound infection. Their domestic health insurance denies the claim for antibiotics and wound care because it’s a complication of an elective cosmetic procedure. Out‑of‑pocket cost: $8,000.
Only if the complication becomes life‑threatening and meets the policy’s definition of a new medical emergency might there be partial coverage. This is why specialized medical tourism insurance (Layer 2) is essential — it’s designed to cover exactly this situation, but only if purchased before travel.
Philadelphia Liposuction confirms that complications from surgery abroad often lead to uncovered follow‑up care.
Now let’s look at the specific steps you should take if a complication arises.
Steps to Take If a Complication Arises at Home
-
Contact the original surgeon or hospital immediately. Request a detailed medical report, including the surgical notes, medications administered, and discharge instructions. This documentation will be critical for any insurance claim.
-
See a local doctor right away. Bring all medical records and the foreign doctor’s report. If they develop infections, scarring or require additional treatment, prompt evaluation is essential — delays can worsen outcomes.
-
File an insurance claim with complete documentation. Even if initially denied, appeal with evidence of medical necessity. Include a letter from your local doctor explaining why the complication requires immediate treatment.
-
Consider a second opinion to verify the treatment plan and cost. Some complications have multiple treatment approaches, and a second opinion can help you avoid unnecessary revisional surgery.
-
Contact your medical tourism insurance provider — if you purchased a policy with complication coverage — to activate direct payment and coordinate care.
UTSW Medical Center advises patients to seek immediate evaluation at home and notify their original surgeon of any complications.
In some cases, you may wonder about legal options.
Legal Recourse and Second Opinions
Legal recourse after returning home is extremely difficult and expensive. The foreign surgeon is not subject to your country’s medical board, and pursuing a cross‑border lawsuit requires navigating different legal systems, language barriers, and jurisdictional challenges. The cost of litigation often exceeds any potential recovery.
The more practical path is to focus on medical care rather than litigation. A second opinion from a qualified local specialist can help determine the best treatment plan and avoid unnecessary revisional surgery. Some medical tourism insurance policies offer access to a medical second‑opinion service as part of their benefits — check if yours does.
Understanding these challenges reinforces why prevention — through proper insurance and planning — is your best strategy.
Frequently Asked Questions
1. Does insurance cover cosmetic surgery when done abroad?
No, standard travel and health insurance policies almost never cover cosmetic or elective surgery performed abroad. These policies exclude planned medical procedures, especially elective ones. Complications from such surgeries are also typically excluded unless a specific medical tourism insurance rider is purchased. If you experience an infection or other complication, you will likely be responsible for all costs. Always check your policy’s “elective surgery exclusion” before traveling.
2. What are the top 3 riskiest surgeries in medical tourism?
The three riskiest surgeries in medical tourism are the Brazilian Butt Lift, tummy tuck (abdominoplasty), and complex spinal fusion. Brazilian Butt Lift carries a high risk of fat embolism. Tummy tucks have high infection and seroma rates. Complex spinal fusion requires extended follow‑up and carries a high complication rate. These procedures are especially risky abroad due to limited follow‑up care and variable hospital standards.
3. Is $100,000 enough for medical evacuation?
No, $100,000 is often insufficient for a long‑distance medical evacuation. An air ambulance from Asia to North America can cost $150,000–$250,000 or more. Regional evacuations may cost $10,000–$50,000. Expert recommendations suggest a minimum of $250,000 in evacuation coverage, and many comprehensive policies offer $1,000,000. Check your policy’s evacuation limit and consider a supplemental rider if needed.
4. What does medical travel insurance not cover?
Medical travel insurance typically does not cover complications from elective or cosmetic surgery, pre‑existing conditions (without a waiver), experimental treatments, or follow‑up care after returning home. It also usually excludes revisional surgery and any costs arising from non‑medically necessary procedures. Always read the exclusions list carefully and consider a specialized medical tourism insurance policy to fill these gaps.
5. What happens if I have a medical emergency after returning home from surgery abroad?
If you have a medical emergency after returning home, your domestic health insurance may deny coverage if the emergency stems from an elective surgery abroad. Domestic policies often classify complications of elective procedures as non‑covered. You could be responsible for thousands in emergency room and hospital bills. The best protection is a medical tourism insurance policy purchased before travel that explicitly covers post‑operative complications.
Conclusion
For anyone considering surgery abroad, the biggest financial risk is not the surgery itself — it’s the uncovered complication. Standard travel insurance leaves you exposed to $50,000–$250,000 in emergency care and evacuation costs. The Insurance Safety Net Framework — Baseline Coverage, Complication Buffer, and Evacuation Parachute — gives you a simple way to evaluate any policy before you travel.
The Insurance Safety Net Framework is more than a checklist; it’s a decision‑making tool. By ensuring you have all three layers, you protect yourself from the most common and costly pitfalls of medical tourism. The few hundred dollars spent on a specialized policy can save you from life‑altering debt.
Before booking your surgery, use the 10‑point checklist from this guide to evaluate your insurance, hospital, and follow‑up plan. Start by comparing three medical tourism insurance policies against the Safety Net criteria. Your peace of mind — and your finances — depend on it.
Disclaimer: This information is for educational purposes and is not a substitute for professional medical or insurance advice. Always consult with a qualified professional.